The Real Cost of Owning a Car in 2025
Understanding what really drains your wallet and smart ways you can save.
3 min. read
Buying a car is one of the most significant purchases most of us will make—but the sticker price is just the beginning. Between financing, insurance, registration, maintenance, and depreciation, the true cost of owning a car can be far higher than most drivers expect. Understanding these expenses is key to making smarter choices, whether you’re buying new, used, or keeping your current vehicle for the long haul.
In this post, the WorkMoney team breaks down the hidden and obvious costs of car ownership, and how you can reduce these expenses.
The Real Costs of Car Ownership
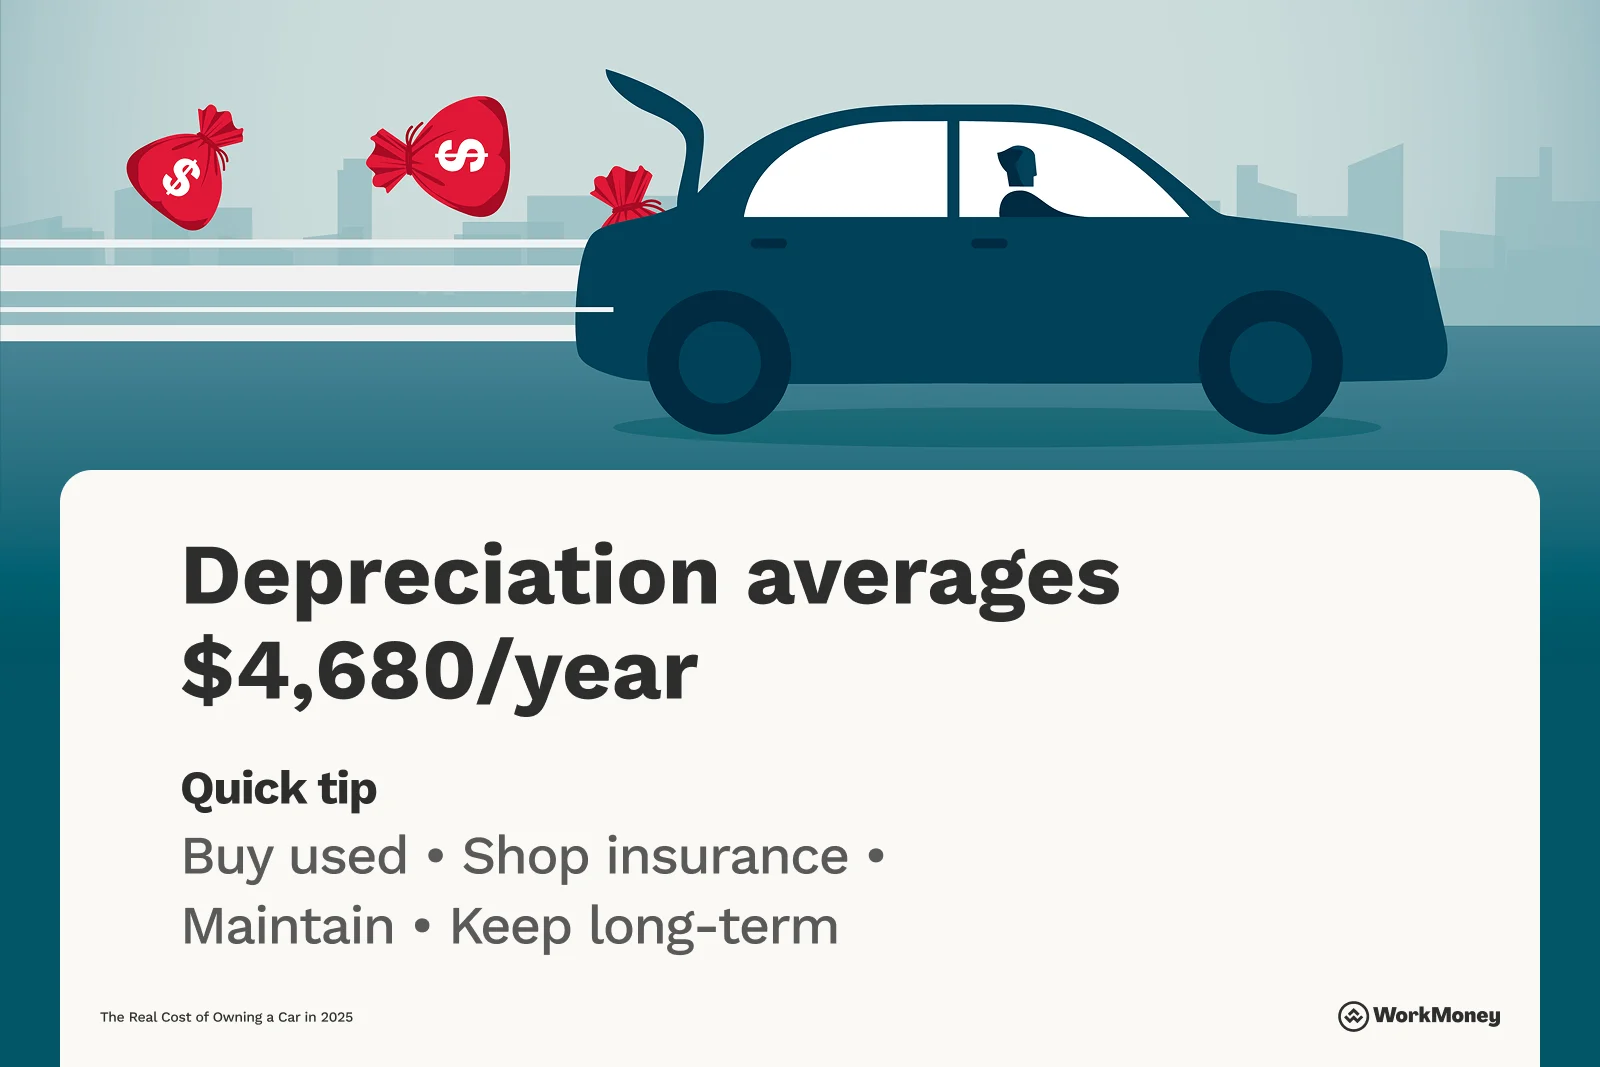
Owning a car is more than just the monthly payment or the price on the sticker. The total cost of driving encompasses everything from the initial purchase to ongoing maintenance and eventual depreciation. New vehicles lose value fast—AAA’s 2024 “Your Driving Costs” study estimates that depreciation alone averages $4,680 per year, and total annual ownership costs can exceed $12,000. Even if you buy a used car, there are hidden expenses that can add up quickly over time.
Lending and insurance are the next biggest contributors. Financing a car means paying interest over the life of a loan, which can add thousands of dollars to the sticker price if rates are high. Insurance costs vary by driver, location, and car type, but it’s rarely cheap, and premiums tend to rise as cars age or if you file a claim. Registration, taxes, and other fees also add up, often catching new owners by surprise.
Maintenance and repairs are inevitable, and while older cars often require more attention, keeping a vehicle long-term usually beats the cost of frequently buying new ones. Tires, brakes, oil changes, and unexpected repairs are part of the deal—but they’re generally more cost-effective than the depreciation hit and higher insurance associated with a new car. To get a clear picture of the total investment, here’s a handy checklist for car ownership costs:
Car Ownership Cost Checklist:
Buying the Car: New or used purchase price, taxes, fees
Lending Costs: Interest on auto loans or financing fees
Insurance: Premiums, deductibles, and coverage options
Registration & Fees: State registration, taxes, and emissions tests
Maintenance: Routine service (oil changes, brakes, tires) and repairs
Depreciation: Loss in value over time
The worst part is that all of these are sunk costs. This is not helping you build wealth for the long term. Having reliable transportation is essential for many, but the key is to keep those costs as minimal as possible. Here’s how you can do that.
How to Reduce the Cost of Car Ownership
Avoid Buying New Vehicles
Buying a new car is an exciting experience, but it can be a significant financial setback. Once you drive the car off the lot, the car is now officially “used” and has lost value. Estimates show new car owners lose 10% in the first month. After three years, it’s 38%. At the five-year mark, cars will lose half their value.
The easiest way to avoid taking the financial hit (and let someone else absorb it) is to purchase a used vehicle. Dealerships typically sell used vehicles after they have inspected and certified them to be functional, and you can potentially get a warranty with it to protect your purchase from potential defects further.
To potentially save even more, you can buy a used vehicle from online marketplaces like Facebook Marketplace, Offerup, or Craigslist. There’s nothing wrong with going this route, but it’s advised to have the car inspected by a mechanic before you buy the vehicle. Ensure that the owner has the title, and fill out any other necessary state documentation.
Shop Your Insurance Around
Car insurance is a necessary cost to protect you in case you get in an accident, and there are dozens of insurers out there that want your business.
If you haven’t looked at your insurance policy coverage and cost recently, there may be an opportunity for you to save money. A recent LendingTree study showed 92% of people who switched car insurance carriers saved money. And of those who switched, 63% saved over $100 or more per year.
Pro tip: If you find a better insurance policy, you can cancel your current policy and receive a prorated refund. Be sure to speak with the insurance agent to ensure you don’t have a lapse in coverage.
Avoid Car Loans, or Keep Your Interest to a Minimum
Whenever you can, it’s best to pay for a car in full. A vehicle is a depreciating asset, and having a loan attached to a depreciating asset only furthers your losses.
For example, if you buy a $20,000 car in full, your losses end there on the price of the car. With a loan, you will pay interest, along with potential fees from the lender. And paying more for a depreciating asset like a car puts the brakes on your wealth building journey.
If you aren’t able to pay for a vehicle in full, that’s okay. A car loan can be helpful to spread payments out and minimize the financial hit. Here are a few things you can do to minimize your loan costs:
Shop around: There are many banks, credit unions, and other financial institutions offering car loans. By shopping around, you can compare and find the best interest rate and loan terms. One LendingTree study showed shopping around could save consumers over $2,300.
Pay off your loan as quick as possible: You never want to end up in a situation where you owe more on a car than its worth. This is called being “underwater” or “upside down.”
Consider refinancing: If interest rates come down, or you’re able to improve your credit score and qualify for a lower interest rate, refinancing into a new loan could cut your loan costs down. Caribou can help you refinance your existing auto loan into a new one, potentially saving you on your loan costs.
Shop Maintenance Costs Around
No matter the vehicle you purchase, there will be regular maintenance needed. You will need oil changes, filters replaced, tires changed and rotated, and much more.
Before running straight to the dealership (which can sometimes be the most expensive option), consider looking into local repair shops as well as national chains like Jiffy Lube, Discount Tire, and Firestone. These brands run specials and sometimes offer coupons to drop the cost even more.
Be Mindful of Your Fuel (or Charging Costs)
Fuel (or electricity if you're driving an EV) will always be a recurring cost. Americans are spending roughly $200 per month on gas. It’s hard to estimate how much EV drivers spend on charging, but the average cost of charging at home is $56 per month.
Regardless of how you need to fuel your car, here are a few easy ways to save.
Use GasBuddy to find the cheapest gas in your area.
Use PlugShare to find chargers in your area (even free ones).
If you drive often, consider signing up for a warehouse club like Costco or Sam’s Club. They often have cheaper gas compared to other local gas stations.
Consider using a cash back credit card that offers additional rebates on your fuel, or EV charging costs
Keep Your Car as Long as Possible
The smartest way to save on a car isn’t trading up every few years—it’s holding onto it. Keeping a car longer spreads that depreciation across more years. Stretching ownership from five to ten years can halve your annual depreciation, turning $4,680 into about $2,340. Even with rising maintenance costs, this is usually cheaper than the costs of a new car—down payments, higher insurance, and renewed depreciation.
And now, cars can easily last over a decade. The average of cars on the road today is just under 13 years. So whether you decide to buy used or new, do your best to keep your vehicle as long as possible to spread the cost of depreciation out.
Final thoughts
Car ownership is a large sunk cost in consumer budgets, but there are plenty of ways to cut these expenses down significantly. The more you can cut these expenses down, the more you can prioritize other financial goals like paying off credit card debt, or begin investing for the future.
Take the next step
Slash your car insurance premiums
Save up to $1,100 a year on your vehicle with Insurify
Easily lower your car loan payments
See if you can save over $1,900 a year by refinancing your auto loan through Caribou.
Was this information helpful?
About the Author
Brett Holzhauer
Brett Holzhauer is a Certified Personal Finance Counselor (CPFC) who has reported for outlets like CNBC Select, Forbes Advisor, LendingTree, UpgradedPoints, MoneyGeek and more throughout his career. He is an alum of the Walter Cronkite School of Journalism at Arizona State. When he is not reporting, Brett is likely watching college football or traveling.