How Much Does Car Insurance Cost?
Find out what car insurance really costs and how to pay less. Your wallet will thank you
6 min. read
If you own a car, car insurance is one of those expenses you can’t skip. But that doesn’t mean you have to overpay for it. How much you'll pay for insurance will depend on different factors, like where you live, your driving record, and even your credit score. Fortunately, there are simple ways to lower your rate and keep more money in your pocket.
Whether you're new to buying car insurance or looking to save, the WorkMoney team is here to show you what it costs and how to get the best deal for your needs.
What’s the Average Cost of Car Insurance?
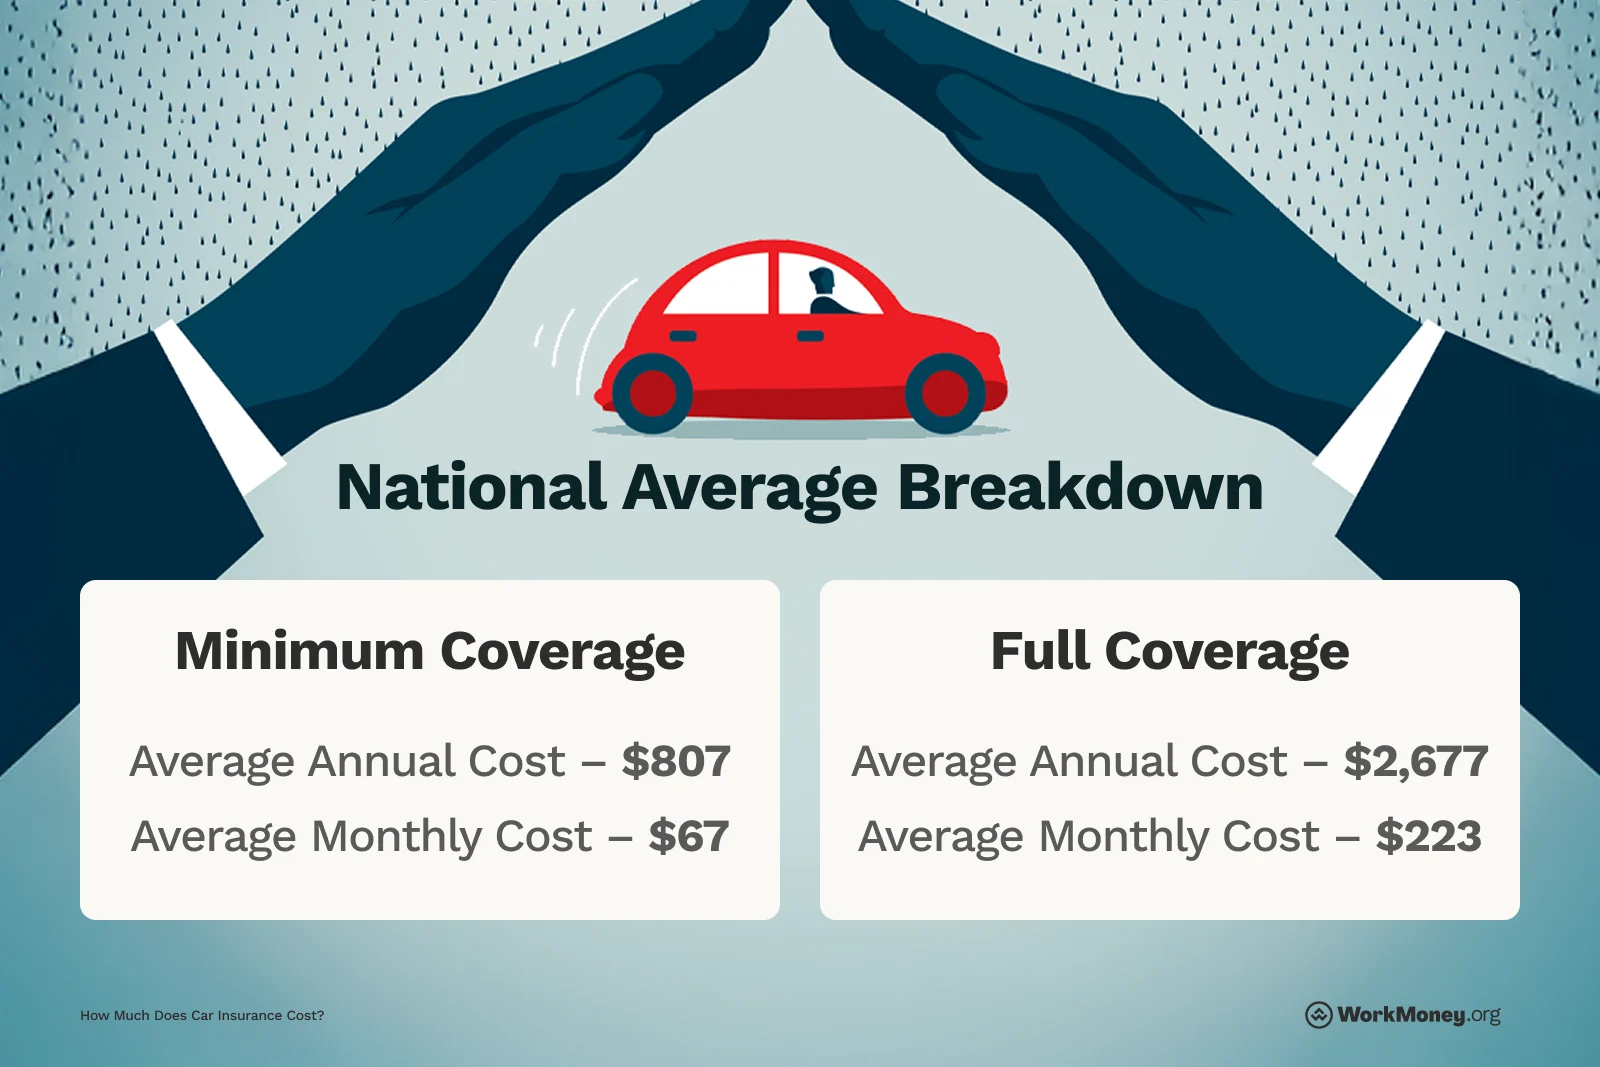
The average cost of full coverage car insurance is about $2,677 a year, according to a July 2025 Bankrate report. And the average price for minimum coverage comes in around $807 per year.
Of course, the amount you'll pay depends on a few key factors, such as where you live, the type of car, and your driving history.
Here’s a simple breakdown of the national averages:
Getting full coverage could mean paying more than three times as much as basic coverage. That’s because full coverage typically includes liability, collision, and comprehensive protection. Minimum coverage, on the other hand, only meets your state’s legal requirements—and usually won’t cover damage to your vehicle.
If you're looking to cut costs, starting with minimum coverage can help keep your monthly payments under $70. But if your car has a loan on it, then full coverage is often required. Either way, comparing quotes is one of the best ways to make sure you're not overpaying.
Coverage Type
Average Annual Cost
Average Monthly Cost
Minimum Coverage
$807
$67
Full Coverage
$2,677
$223
What Affects How Much You Pay?
Ever wonder why your car insurance costs more than your friend's? It's because insurance companies use a mix of personal and driving-related details to determine your rate. Here are some of the things they likely take into consideration:
Age and Gender: Drivers under age 25 tend to pay more, and some states also charge more for men than for women.
Driving Record: Tickets, accidents, or a DUI can also raise your rate. Maintaining a clean driving record helps keep costs down.
Credit Score: In most states, a lower credit score can mean a higher premium, even if you’ve never had an accident.
Where you live and park: City drivers often pay more because of higher theft and accident rates. Using garage parking or anti-theft features helps lower costs.
Vehicle Type: Newer or high-end cars typically cost more to insure—especially if repairs are expensive.
How much you drive: More miles can mean higher rates, especially if you commute. Light driving usually costs less.
The type and amount of coverage you'll need will also affect your final cost. If your policy has larger payout amounts, extra protection like collision coverage, or a lower deductible, you'll typically pay a higher monthly premium.
Your State Affects Car Insurance Rates
Where you live has a big impact on what you’ll pay for car insurance. Each state sets its own rules, and things like accidents, theft, and weather can either raise or lower your costs. Take a look:
High-cost state: Nevada is one of the most expensive states—full coverage averages $3,639 a year, and minimum coverage is $1,086.
Lower-cost states: Full coverage in Idaho and Vermont is much cheaper at around $1,400 per year, and minimum coverage less than $400 yearly.
You can check out your state’s average with this free Bankrate tool.
How Your Credit and Driving Habits Affect Car Insurance
Credit Score:Most insurance companies now use credit‑based insurance scores instead of standard credit scores to help predict the likelihood you'll file a claim. A low score often leads to higher car insurance rates, even if you don't have any accidents or tickets. These seven states currently ban this practice: California, Hawaii, Maryland, Massachusetts, Michigan, Oregon, and Utah.
Usage-Based Insurance (Telematics):
Sometimes insurance companies may offer discounts if you allow them to use a mobile app or plug-in device to track your driving habits. They’ll look at things like:How far you drive
When you drive
How safely you drive (like avoiding hard braking or speeding)
Who Benefits:
Drivers who don’t drive much
People with safe driving habits
Anyone looking to save more on their premiums
These programs are optional and can offer discounts of up to 40%. It’s a smart way to lower your costs—especially if you’re already a careful driver.
Real Ways to Lower Your Insurance Costs
Sure, car insurance can feel like just another bill. But there are ways you can still save money without giving up the coverage you need.
Let's take a look at a few options worth checking out:
Compare Car Insurance Rates with Insurify
You can use an online comparison tool like Insurify to help you shop multiple insurers at once and save a lot of money. Insurify reports that users have saved an average of $1,025 per year by comparing quotes.
Refinance Your Auto Loan with Caribou
Refinancing your car loan can free up monthly cash, making it easier to afford insurance. Caribou users save around $130 per month on average, which adds up to more than $1,500 per year.
Know Your Options If You’re Struggling to Pay
If money is tight or you don't have the best credit, there are still other ways to save on your car insurance:
Ask your insurance agent about flexible payment plans.
Consider buying only the minimum coverage necessary to help you temporarily lower costs.
Check into state programs. California, Hawaii, or New Jersey all offer low-cost insurance programs that provide reduced rates for eligible drivers.
Explore usage-based or pay-per-mile insurance. This offers discounts to low-mileage or safe drivers.
A few other options that could help you make room in your budget include:
Lifeline – A federal program that helps reduce your phone or internet bill.
LIHEAP (Low-Income Home Energy Assistance Program) – Offers assistance with energy costs.
These programs don’t reduce your car insurance directly. But they can help you cover other essentials, so more of your income is available for what you need. Many people don’t realize they qualify for these types of support, so it’s always worth asking.
How Car Insurance Costs Impact Your Budget
It's no secret that every dollar counts. So finding ways to keep your car insurance costs low can make a huge difference in your everyday.
What You Could Do with the Money You Save
Even a small savings of, let's say, $60 per month will put less stress on your finances. You could then put that money towards other financial needs, such as:
Cover a monthly utility bill (the average U.S. household spends around $150 per month on electricity bills).
Pay extra toward credit card debt or other high-interest bills.
Create an emergency fund to handle unexpected expenses.
The best part is that small savings can add up over time and give you more flexibility in your budget.
Savings Checklist
Use this quick reminder to help lower your insurance costs and create more room in your budget:
Compare insurance quotes at least once a year.
Try usage-based or pay-per-mile insurance if you drive infrequently.
Refinance your auto loan to free up cash for coverage.
Adjust the amount of coverage you buy as your car gets older.
Look into income-based assistance or state programs if you qualify
Final thoughts
Buying car insurance doesn’t have to wreck your budget. Doing a little research, like comparing quotes, adjusting your coverage, or looking for discounts, can make a real difference.
Every dollar you save on insurance is a dollar you can put toward something else that matters, such as paying bills, building savings, or tackling debt.
Take the next step
Slash your car insurance premiums
Save up to $1,100 a year on your vehicle with Insurify
Easily lower your car loan payments
See if you can save over $1,900 a year by refinancing your auto loan through Caribou.
Was this information helpful?
About the Author
DeShena Woodard
DeShena Woodard is a Financial Freedom Coach, Certified Life Coach, freelance personal finance writer, and podcast host. Her story, advice, and expertise have been featured in prominent outlets such as CNN Underscored, Business Insider, Yahoo Finance, NerdWallet, and more. Through her platform, Extravagantly Broke, she helps women take control of their finances with simple, stress-free strategies—without sacrificing the joy of everyday life. When she’s not writing or coaching, DeShena enjoys traveling, biking, and spending time with her family.