2025 Steps to Buying a House
Clear, step‑by‑step guide to buying your first home in 2025
8 min. read
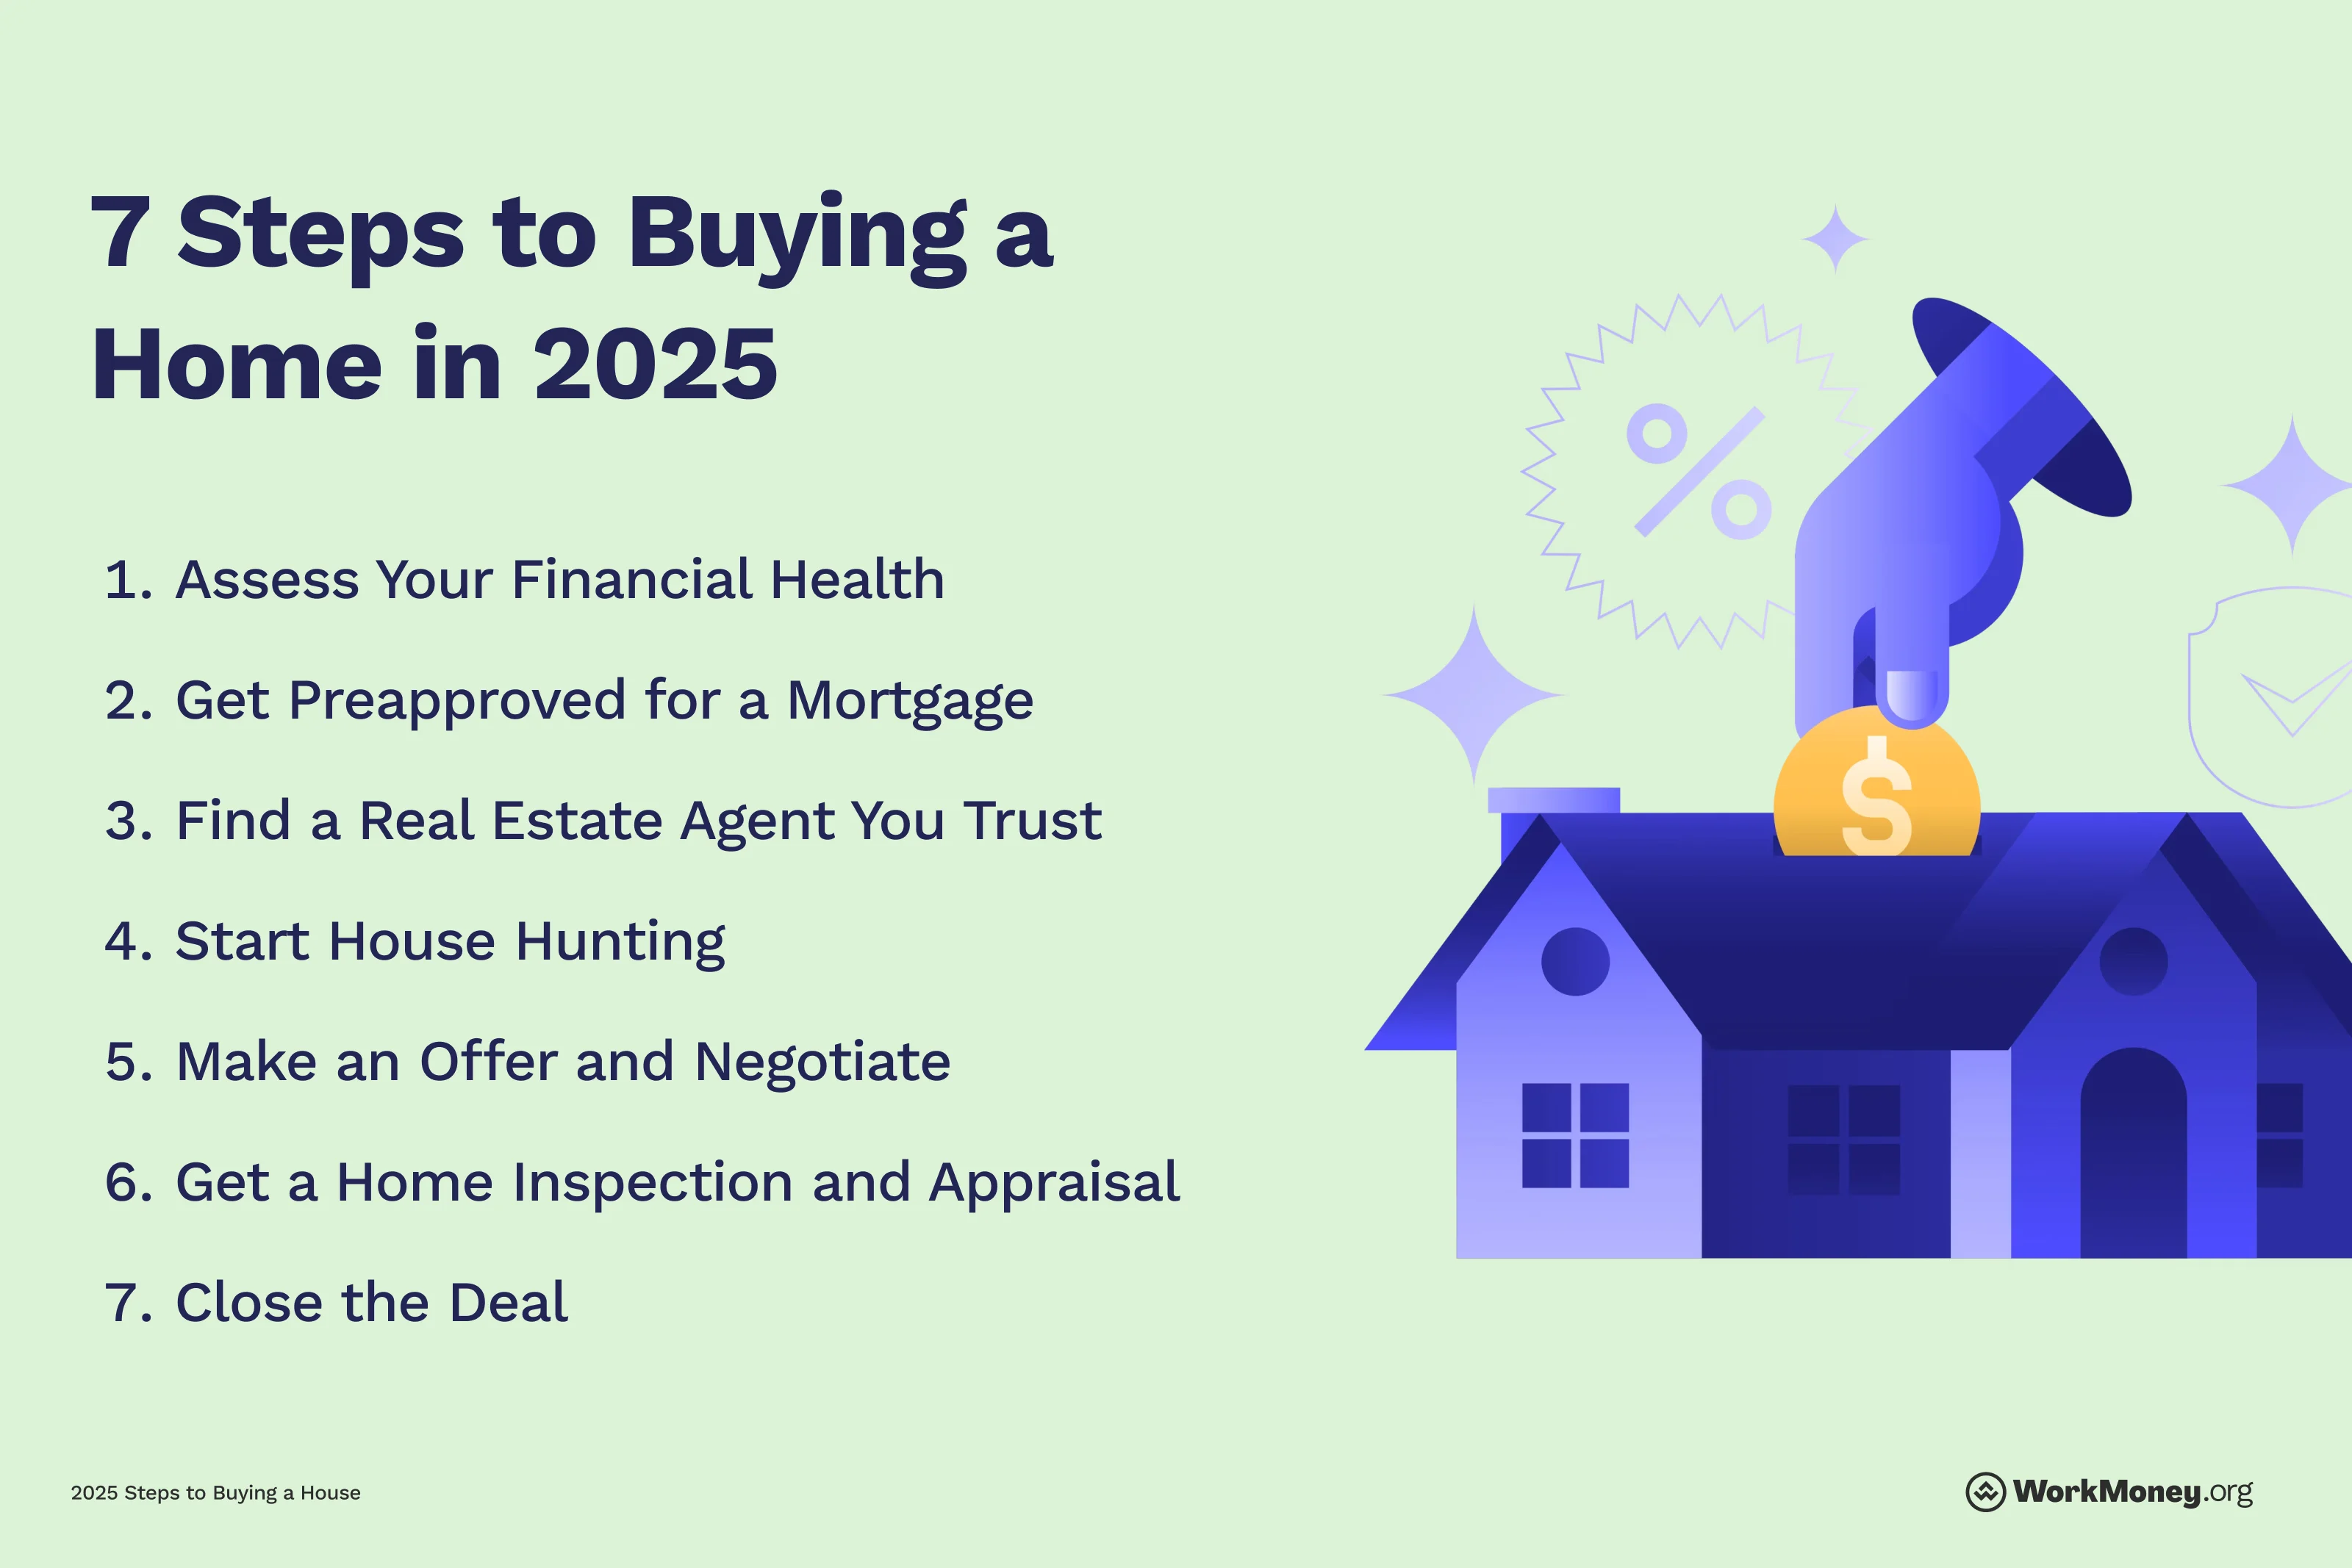
Step 1: Assess Your Financial Health
Homeownership can be a fantastic investment over the long term. The idea is that you lock in the price of your home, pay it down over time, and the value of your home should increase. The goal is that by the time you near retirement, your home may be nearly or completely paid off, and it has increased in value.
However, this long-term investment comes with one important factor: you will be able to maintain monthly payments, as well as needed maintenance on the home, without stretching yourself financially thin. This is typically considered spending more than 30% of your income to housing costs, and now, more than 25% of middle-class households are in this category.
This is a slippery slope. If someone loses work or an unexpected bill comes up, it could put a household in a financial bind. To avoid this, it’s vital to run the numbers to see if you’re financially ready to dive into homeownership. Here are the financial aspects to consider when evaluating if you’re ready to be a homeowner:
Credit score and credit reportYour credit score is your financial report card given to you by banks. A credit score can range from 300-850, the higher it is, the better. And when it comes to buying a house, a higher credit score will likely give you a lower interest rate on a mortgage.
A credit report is a detailed list of all your credit activities, with both good and bad remarks. This is what banks will refer to when you’re looking for a mortgage lender.
Even if you decide that homeownership isn’t the best option, it’s important to look at this report at least yearly. This is because there may be errors on your credit report that are negatively impacting your chances of qualifying for a mortgage, credit card, auto loan, or other financial product. You can get your credit report annually for free here. If you happen to find an error, it’s best to report it to the correct credit reporting agency.
Debt-to incomeOne of the first metrics a bank or other financial institution will measure is your debt-to-income ratio. This is calculating your gross income against how much debt you currently have. Here’s how it works:
Let’s say you make $4,000 per month. If you currently have $1,000 in debt payments between a car loan and credit cards, your DTI is 25%. Lenders want to see potential home buyers stay under 43%. So if you’re currently close to 43%, it’s probably best to pay down your existing debt before taking on a home loan.
Saving for a homeIf the previous two points are an easy hurdle, that’s a good sign. Now, it’s evaluating how much you have saved up for the upfront costs. These include the initial down payment and closing costs. This will vary widely based on how much you plan on spending on your home purchase. A down payment can range anywhere from 3-20%, and closing costs are typically 3-5% of the home price.
So if you aim to purchase a $400,000 home, you will need:
Between $6,000 and $80,000 for a down payment
Between $12,000 and $20,000 for closing costs
It can be tempting to keep your down payment as small as possible, but this will likely bring your monthly payment higher. So the more you can put down, the less your monthly payment will be.
Step 2: Get Preapproved for a Mortgage
Before you run out to see homes, it’s vital to get preapproved for a mortgage. Preapproval simply means that a lender is ready to give you the money you need to purchase a home, and how much they’re willing to lend you.
You can find a mortgage loan officer at your local bank, credit union, or you may even know one personally. They will be your point of contact from preapproval to closing. Each one may have a slightly different loan application process, but they will generally ask for these documents:
📄 Personal Identification
Government-issued photo ID (e.g., driver's license or passport)
Social Security number
💼 Income Verification
2–3 recent pay stubs
💰 Employment Verification
Contact info for your employer (for verbal or written verification)
Employment letter (sometimes requested)
🏦 Asset and Bank Information
Bank statements (last 2–3 months for checking, savings, or other accounts)
Investment account statements (401(k), IRA, brokerage, etc.)
Proof of funds for down payment (gift letters if money is gifted)
🧾 Debt and Liability Info
Monthly debt obligations (credit cards, auto loans, student loans, medical debt, etc.) If you’re currently paying on medical debt, DollarFor may be able to help you either reduce or eliminate it.
Current mortgage statements (if you own other properties)
Rent payment history (if applicable)
Once they verify these documents, they will tell you the type of mortgage you can qualify for, and how much you’re able to spend on a home.
The key: talk to multiple lenders. They are all competing for your business, and they will do everything in their power to get you a lower rate – resulting in significant savings.
Step 3: Find a Real Estate Agent You Trust
A great real estate agent can help you navigate the process of buying a home, setting up house showings, and coordinating the closing process seamlessly. However, keep in mind that there can be agents that are less than great, so be sure to look into online reviews and potentially get a referral from someone you trust.
Keep in mind that you’re paying them to represent you in this important purchase, so you should be asking specific questions to ensure they are the right fit for you. Here are a few questions to get started:
How long have you been in real estate, and how many deals have you closed recently?
Do you specialize in this area and property type?
What’s your strategy for helping me buy/sell in this market?
Do you work full-time or part-time?
Will I be working directly with you or someone on your team?
How often will you communicate with me, and how?
How many clients are you currently working with?
What’s your commission rate, and are there any other fees I should know about?
Can you recommend trusted lenders, inspectors, or contractors?
Can you share recent client reviews or references?
Step 4: Start House Hunting
Once you find the right real estate agent, or decide to represent yourself (it’s not required to have an agent), it’s time to start looking at homes.
The best way to start doing this is by using platforms like Zillow or Redfin. You will be able to see homes in the area you want, and at specific price points.
Once you find one or more homes you’re interested in, either have your agent set up showings or schedule a showing with the listing agent directly. On average, buyers will look at between 8-10 homes before they put in an offer.
However, much of this is dependent on whether it’s currently a buyer's or seller's market. You can talk to an agent to get their perspective, and even dive into specific data offered through Redfin or the National Association of Realtors.
Step 5: Make an Offer and Negotiate
Once you find the home that fits your needs and your budget, it’s time to make an official offer. In a typical offer letter, you will list the price you’re willing to pay for the home, any contingencies you may have (i.e. any repairs, buyers credits, etc), and a proposed closing date.
Here are a few tips after you submit your offer:Prepare for Negotiations: The seller may counter your offer—be ready to respond quickly with your agent’s guidance on price, closing date, or contingencies.
Stay in Close Contact with Your Lender: Finalize your mortgage application, submit any additional documentation, and lock in your interest rate if you haven’t already.
Avoid Major Financial Changes: Don’t open new credit lines, make large purchases, or change jobs—these can affect your mortgage approval.
Step 6: Get a Home Inspection and Appraisal
Once you have your offer approved, you’re officially under contract! Now begins the heavy lifting.
From here, you will now need to schedule a home inspection where a professional comes out to identify any potential issues or defects with the home. This is the responsibility of the buyer to schedule and pay for. A home inspection can range anywhere from $250-600. You can readily find inspectors by searching online. Similar to agents, be sure to look at online reviews to find one with a better customer experience.
Once the inspection is done, you’re given documents going over any issues with the home. You can then use this as negotiating power with the seller. For example, if the water heater needs to be replaced, you can ask for a buyer's credit towards the purchase of a new one once you’re the owner.
Additionally, if the home has far too many repairs or issues than you’re comfortable with, you can walk away from the deal. The only thing you will lose is the money for the inspection.
Step 7: Close the Deal
Once the inspection and negotiation process has concluded, it's time for the lender to step in and begin underwriting the home for a loan. At this point, it’s important to stay in close communication with your lender and agent to respond quickly to requests for documents and avoid making any major financial changes.
From there, you will likely have a final walkthrough of the home a few days before the official closing, and then you will collect the keys to become an official homeowner!
Was this information helpful?
About the Author
Brett Holzhauer
Brett Holzhauer is a Certified Personal Finance Counselor (CPFC) who has reported for outlets like CNBC Select, Forbes Advisor, LendingTree, UpgradedPoints, MoneyGeek and more throughout his career. He is an alum of the Walter Cronkite School of Journalism at Arizona State. When he is not reporting, Brett is likely watching college football or traveling.